03 · Engines
Three cash engines. One energy option. No $1 billion fairy tale.
Phase 1 of the holding is Markets, Jewels and Labs. Ethiopia’s 2025/26 export year was a record 10.7 billion dollars — coffee $3.0M, gold a top earner. That is the weather. It is not AURION’s revenue.
Two pictures of the same decade
Sponsor path interpolates the holding plan’s $0.5M → $5M → $100M → $1B print. Independent path is a well-run specialty exporter plus a jewelry workshop that actually ships. Power cash is not in either line.
Indep. Y3 revenue
$1.55M
Markets + Jewels + Labs
Indep. Y10 revenue
$29M
Still an SME+
Indep. Y1 EBITDA
−$140k
Burn. That is normal.
Sponsor Y10
$1.00B
Requires industrialised Power + mining
markets
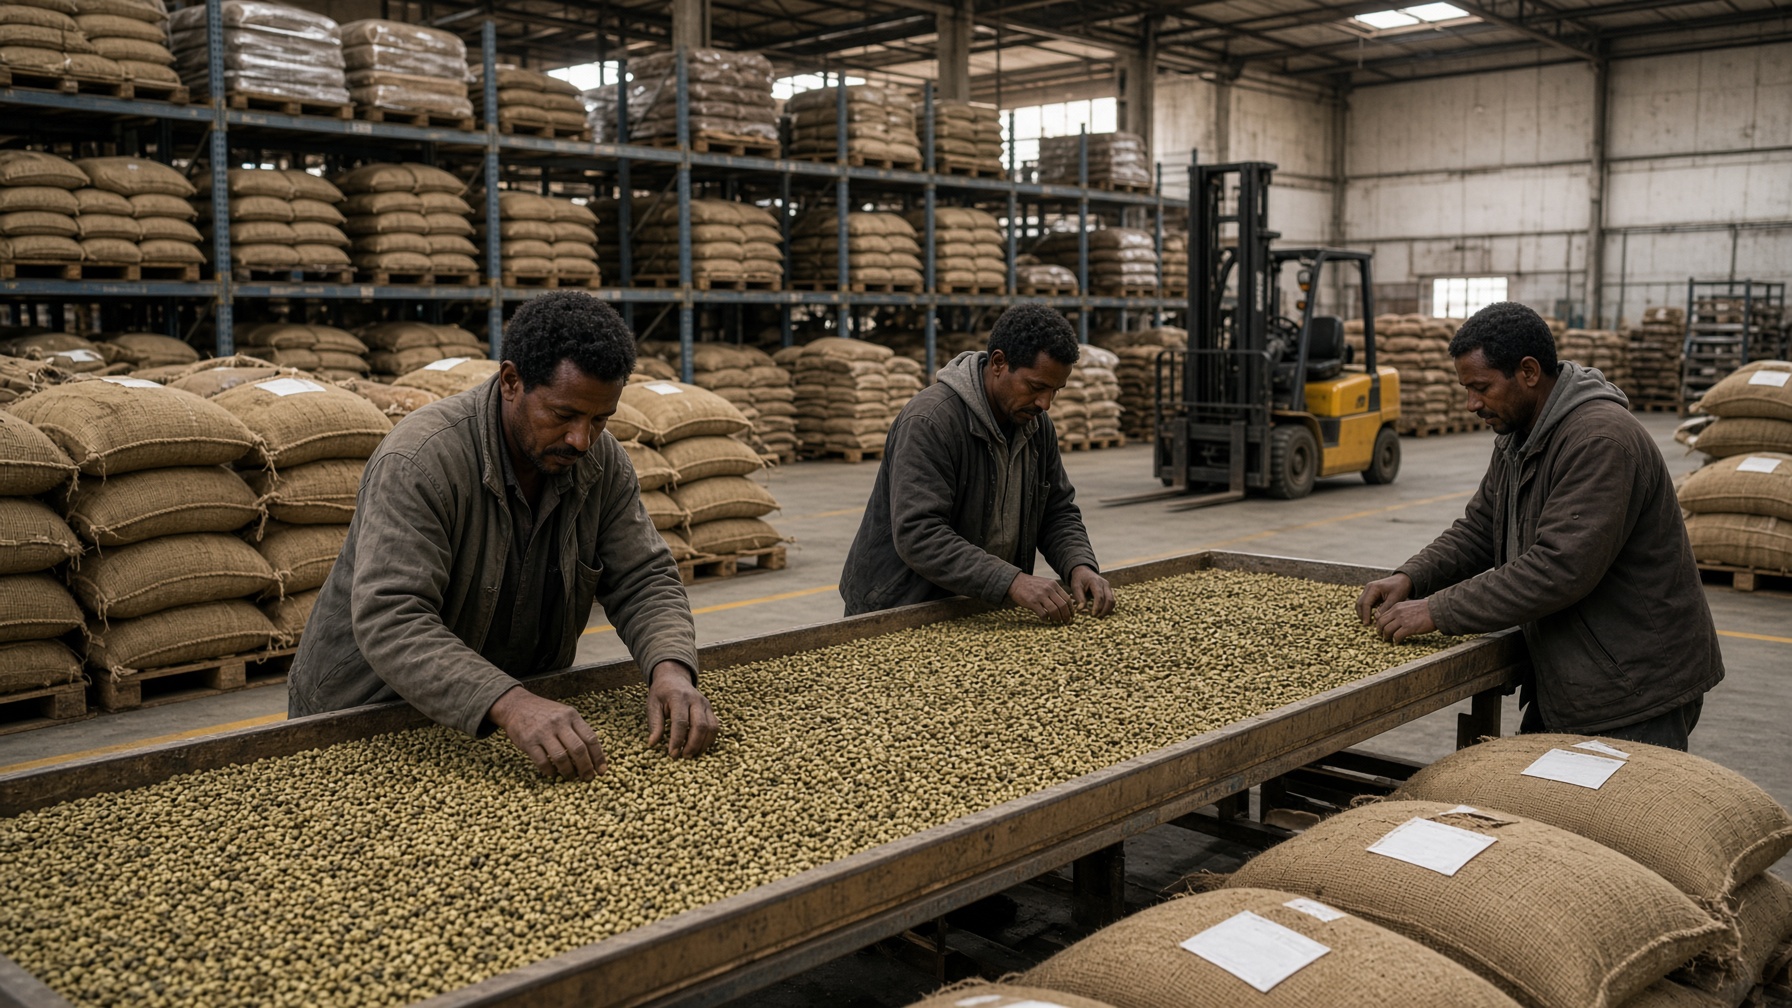
AURION MARKETS
A curated export gateway for Ethiopian goods — not Jumia, not Amazon.
- Commission 10–15% on D2C (independent; sponsor prints 10–25%)
- Seller subscriptions $29–$299/mo — only after GMV is real
- Logistics margin 10–20% on consolidated export lots
- Ads and data are year-3+, not year-1
| Year 1 independent | Year 3 independent | |
|---|---|---|
| Vendors | 40 | 180 |
| Buyers | 2500 | 18000 |
| GMV | $400k | $4.0M |
| Take rate | 15% | 15% |
| Revenue | $60k | $600k |
Red team
- Payments: Telebirr is domestic. Cross-border D2C needs a licensed acquirer and a written FX path. USDC is not a design — NBE notices of 27 Feb 2026 and 23 Jul 2026 prohibit virtual-asset exchange, transfer and custody unless expressly authorised.
- Trust: Ethiopian D2C has a counterfeit and delayed-shipment problem. QC hubs in Addis are the product.
- Logistics: Ethiopian Airlines Cargo is an advantage only with rates on paper. EMS is not a luxury last-mile.
- The $6B diaspora TAM is not obtainable. A 0.03% share of that TAM is already a good year-3.
Gates
- Export licences per category (coffee via ECX/ECTA rules, honey phyto, textiles origin)
- Payment stack: Telebirr + a licensed card acquirer + documented FX repatriation
- 50 live SKUs, 20 vendors, 3 destination countries before Seed is spent on ads
jewels
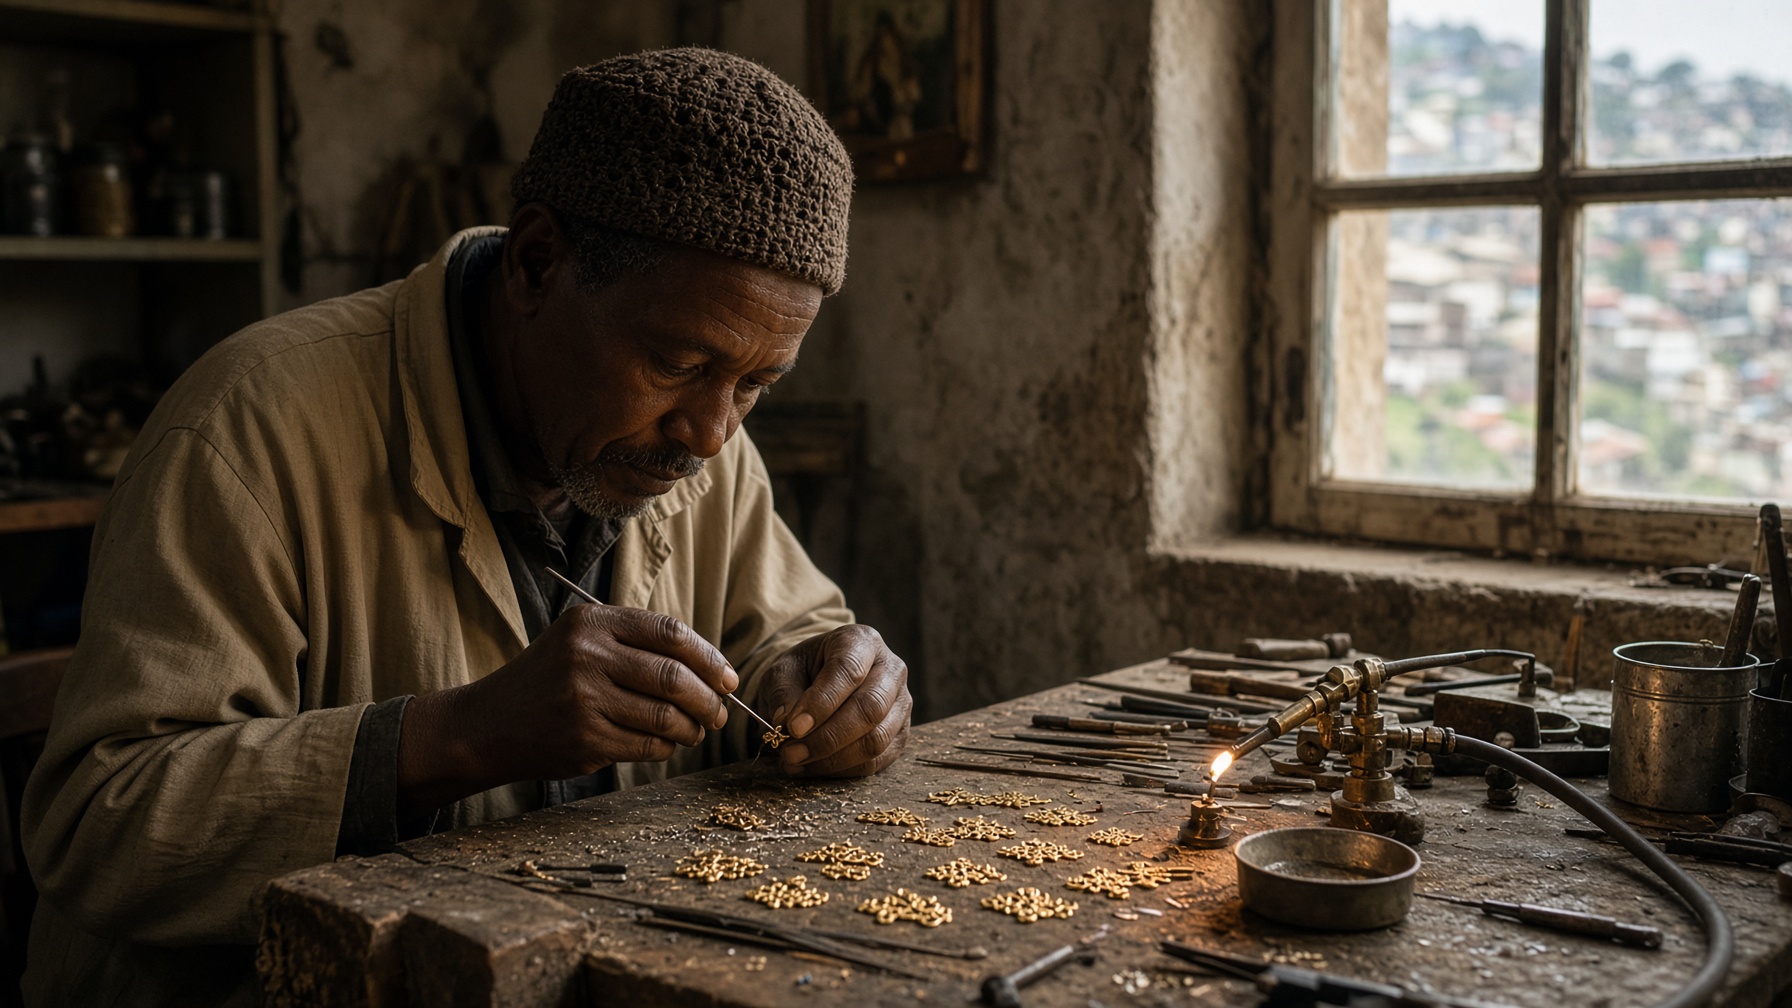
AURION JEWELS
Finished jewelry from Ethiopian gold and gemstones. The margin is in the bench, not the bar.
- B2B white-label and small D2C collections
- Workshop in Addis → SEZ factory only after a $1M+ order book
- Independent gross margin target 40% at scale; 18–25% in years 1–2
- Sponsor 30–45% EBITDA is a mature luxury print, not a year-1 workshop
| Year 1 independent | Year 3 independent | |
|---|---|---|
| Pieces | 400 | 1800 |
| ASP | $200 | $500 |
| Revenue | $80k | $900k |
Red team
- FY2025/26 gold export boom is bullion. Jewelry is a different licence, a different buyer, and a different ESG file.
- Mineral Transaction Proclamation 1144/2019: crafting, refining and export certificates are not automatic with a PLC.
- Conflict, child-labour and ASM (artisanal) gold are the first question a EU/US buyer will ask. Traceability is the product.
- SEZ Proclamation 1322/2024 four-year rent holiday is real policy. An IPDC allocation is not in hand.
Gates
- Assay + hallmarking path, export certificates, responsible-gold SOP
- Named offtake (even a $150k first collection) before Series A factory CAPEX
- No related-party gold from a future AURION RESOURCES until that SPV exists
labs
AURION LABS
File patents. Do not book royalties.
- Year 1–3: 2–3 utility filings (safety sensor, agri-IoT, energy monitor) plus design patents on jewelry
- Revenue is option value until a licence or a product ships
- Independent year-5 labs revenue $0.14M; sponsor 60%+ EBITDA is a terminal-state cartoon
| Year 1 independent | Year 3 independent | |
|---|---|---|
| Filings | 2 | 5 |
| Revenue | $0k | $50k |
Red team
- Ethiopian, ARIPO and USPTO/EPO filings are cash out the door for 4–7 years.
- A patent is not a product. A product needs a buyer. Labs does not carry the holding.
- Energy-monitor IP must not be circularly ‘valued’ against STAR KEY.
Gates
- Counsel-led filing plan with a budget, not a slide of 15 patents by year 5
- One working prototype before Seed is described as an ‘IP engine’
Holding findings
Do not concatenate $3.6M and $1.86B
The holding plan’s Phase-4 $1B revenue print assumes energy and mining have already industrialised. They have not. Two capital stacks, two boards, two CIMs.
Diaspora TAM is not a forecast
4M × $1,500 = $6B is a ceiling, not a funnel. Independent year-3 Markets GMV $4M is already a well-run specialty exporter.
Jewelry EBITDA 30–45% is a destination
Year-1 is a bench and a collection. Factory CAPEX waits on offtake. Gold-export headlines are bullion, not filigree.
Labs will not pay the rent
Patents are real work and negative cash. Keep the budget. Strip royalties from any holding model a lender might see.
Dual-class stock is not a closing condition
10:1 founder votes are a US-tech habit. Confirm under the Commercial Code before promising control in a term sheet.
Power is the fourth engine and a different raise. Read financials and the roadmap.